Now raising · Accredited investors only
Metro Atlanta Multifamily
A ~1,000-unit multifamily community in metro Atlanta, bought at a distressed basis after the prior owner ran out of capital. Closed, with new management in place. Jetstream is raising capital alongside the sponsor to complete the capex plan.
Get the deal highlightsCapital raised
$13M of $20M
$7M remaining · as of Nov. 5, 2026
- Units
- 997
- Built 1987–1989
- Purchase price
- $73.0M
- ~$73K per unit, closed
- Basis vs. 2023 appraisal
- ~40% below
- $122.1M as-is appraisal
- Minimum investment
- $50K
- Through Jetstream’s fund
The property
What you’re investing in
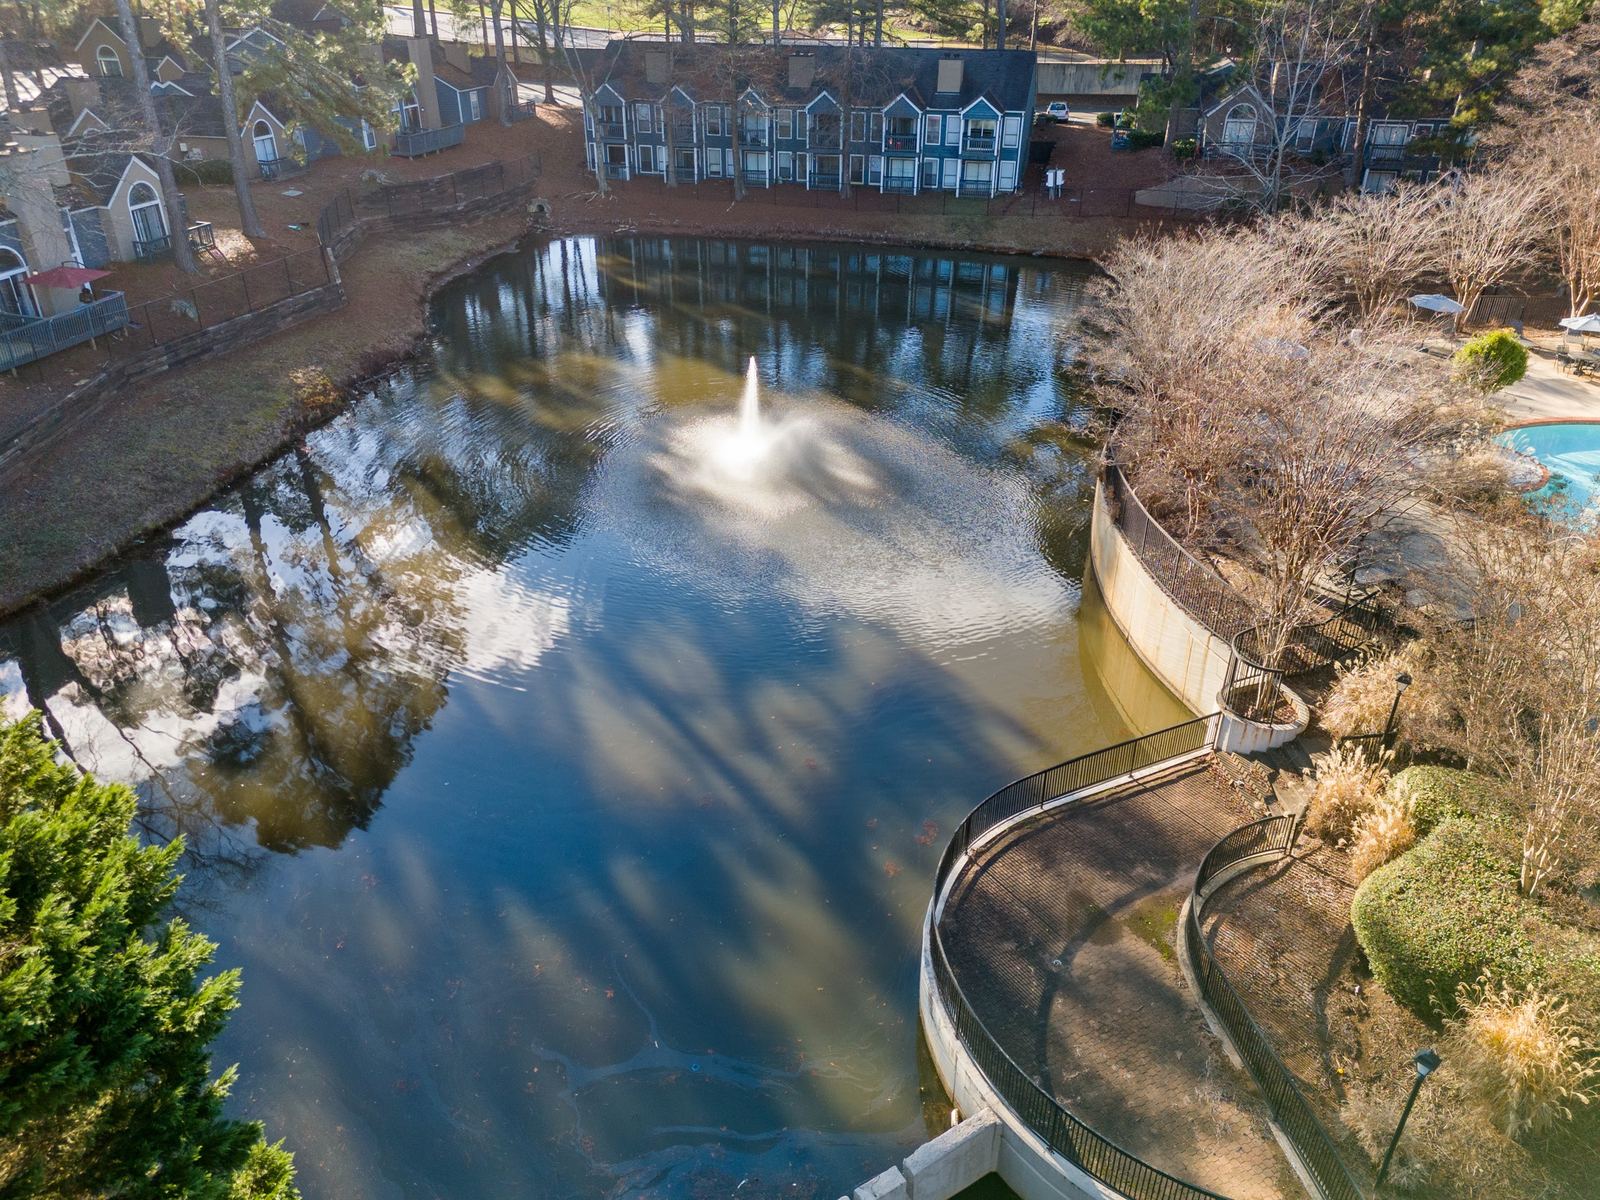
A 997-unit community in metro Atlanta with a pond, clubhouse, indoor and outdoor pools and a fitness center. Interior photos show renovated model units.
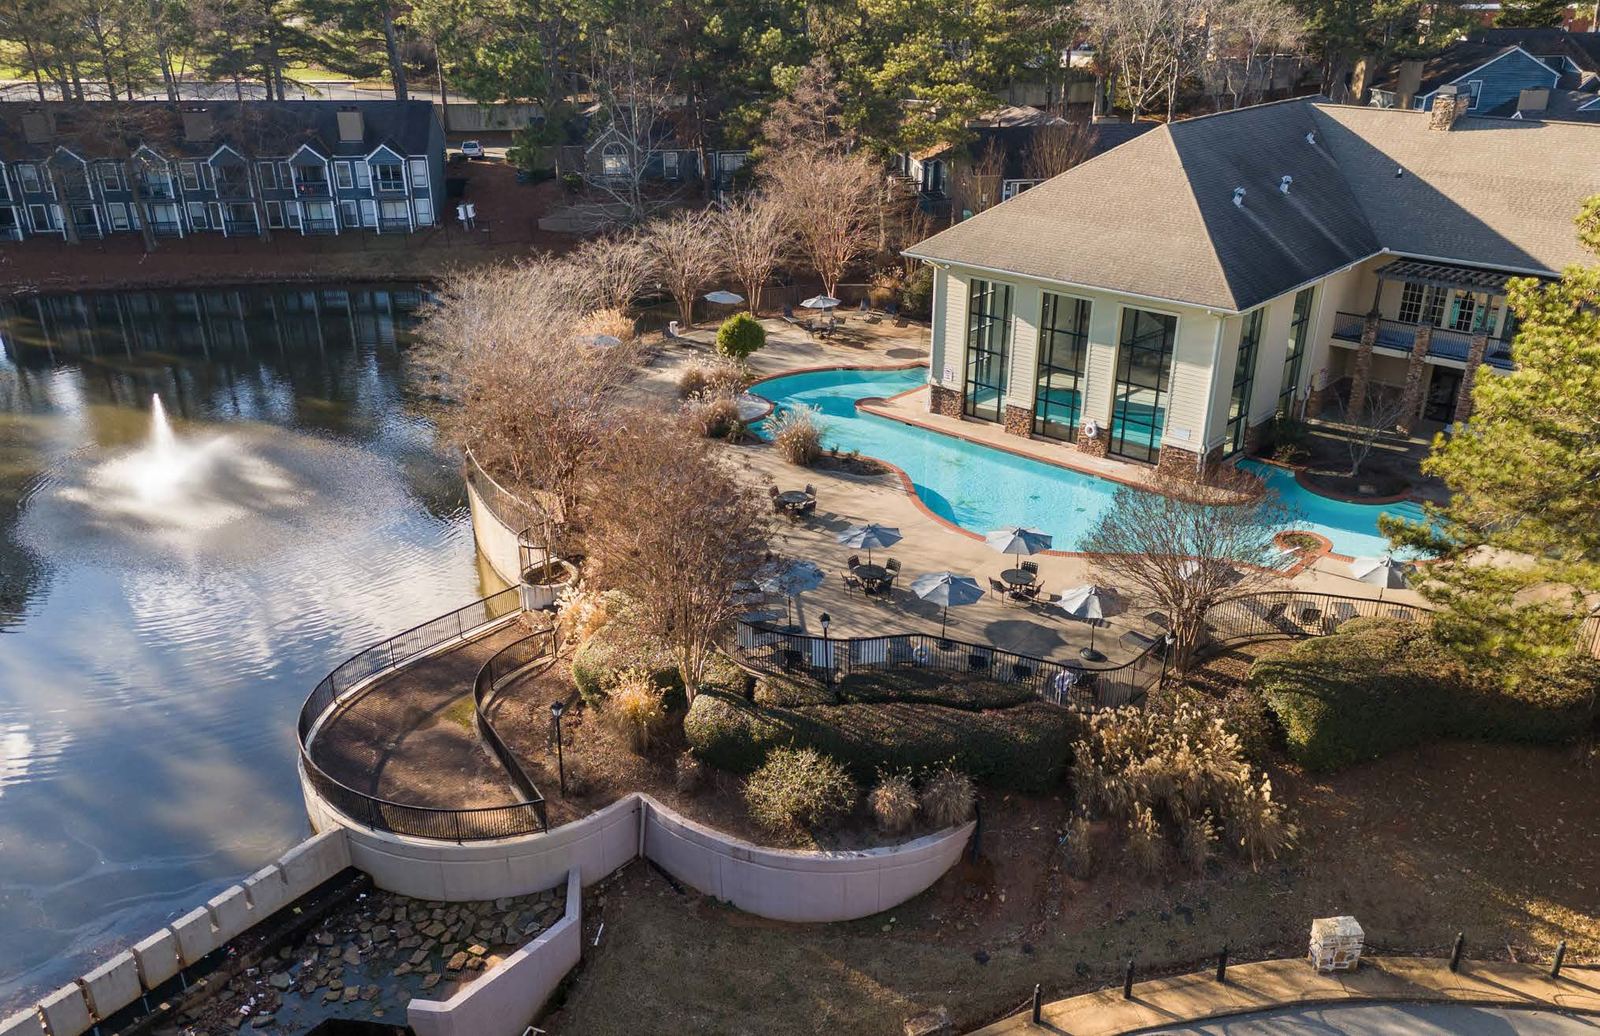
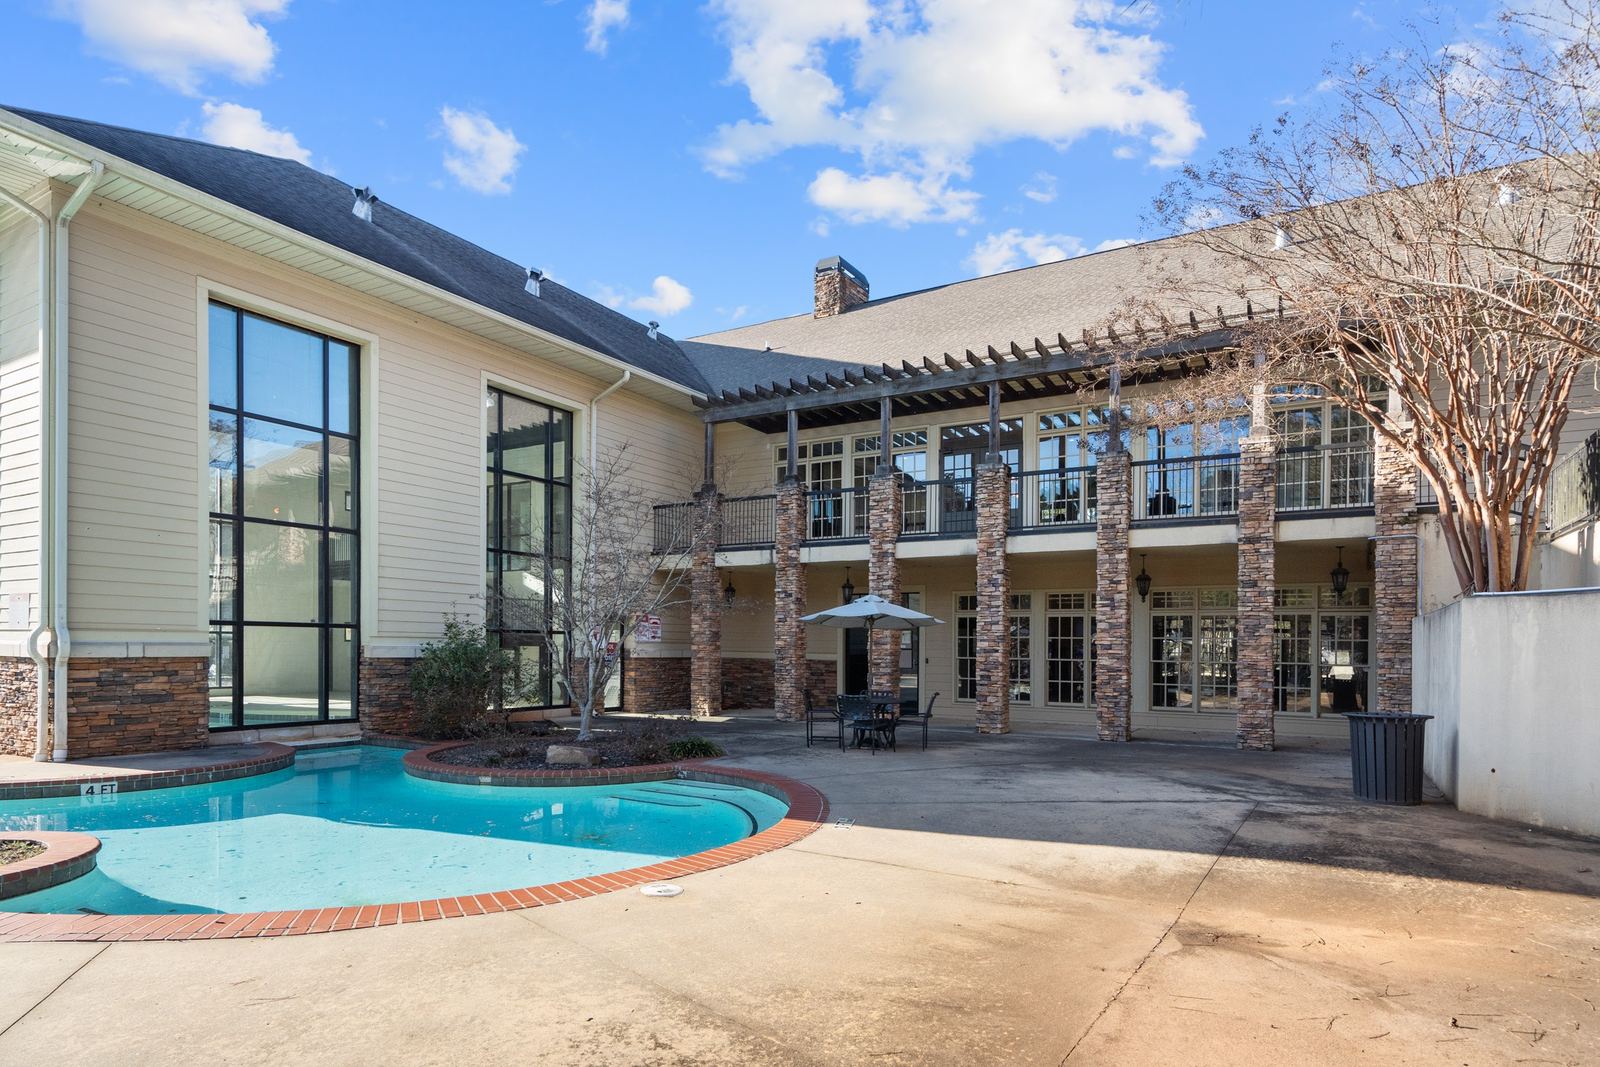
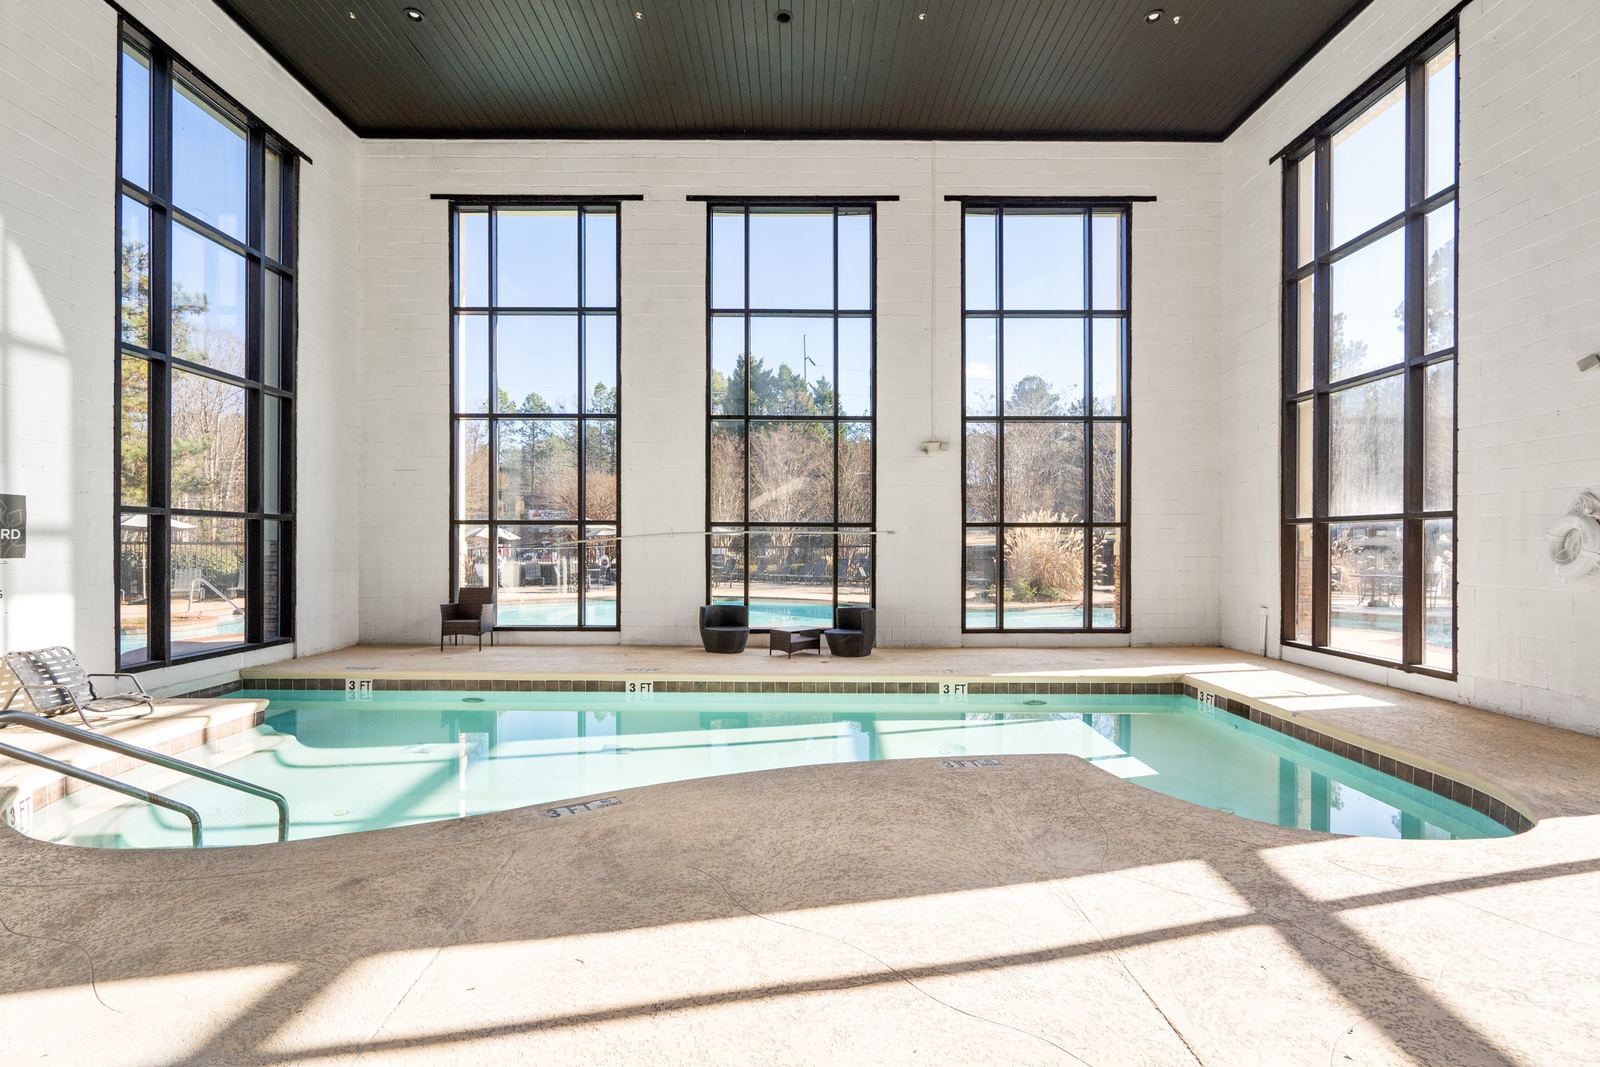
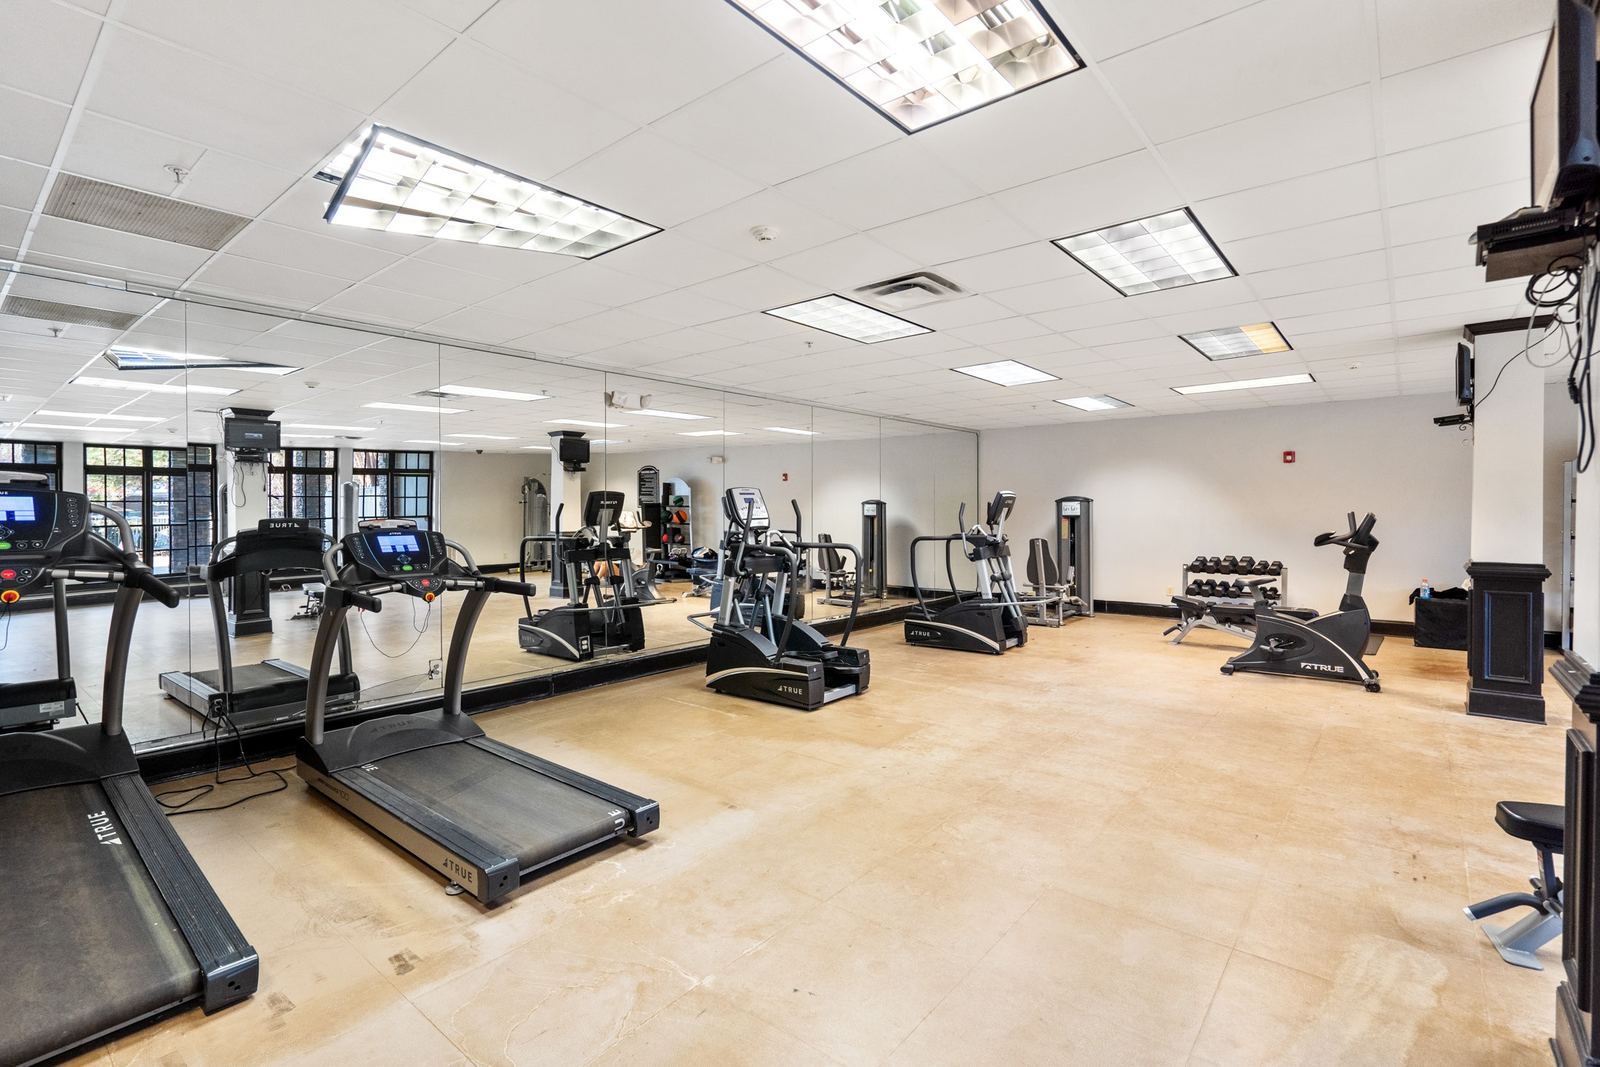
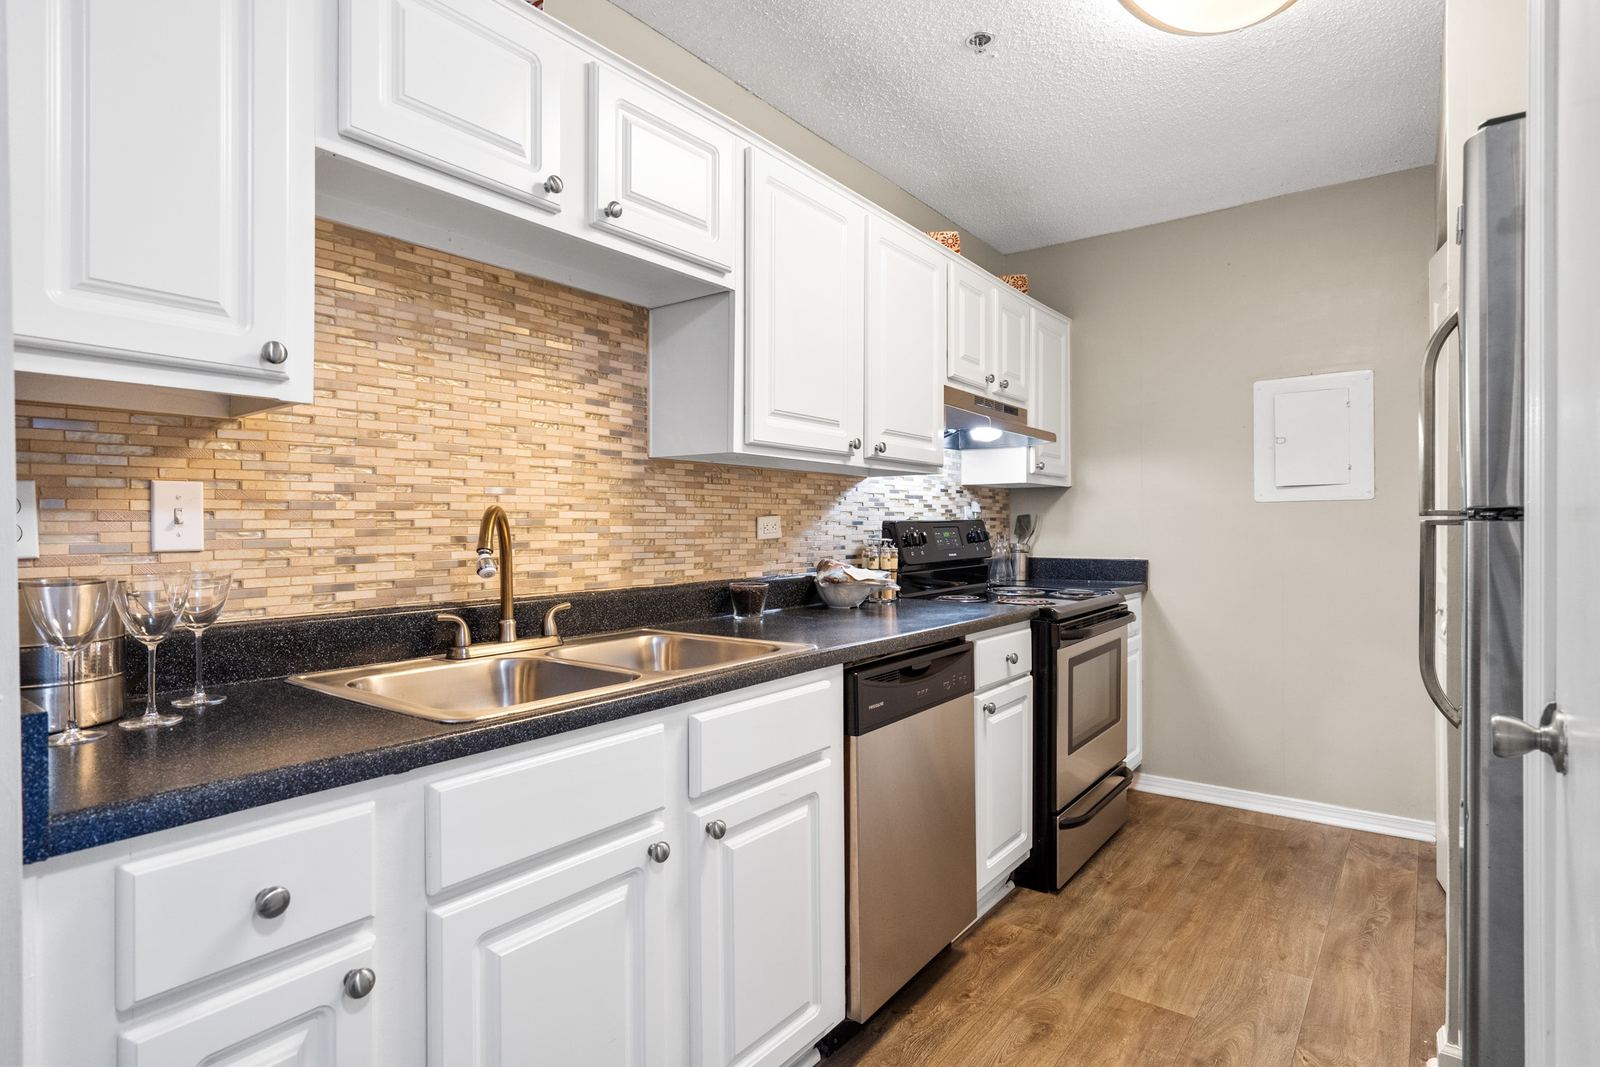
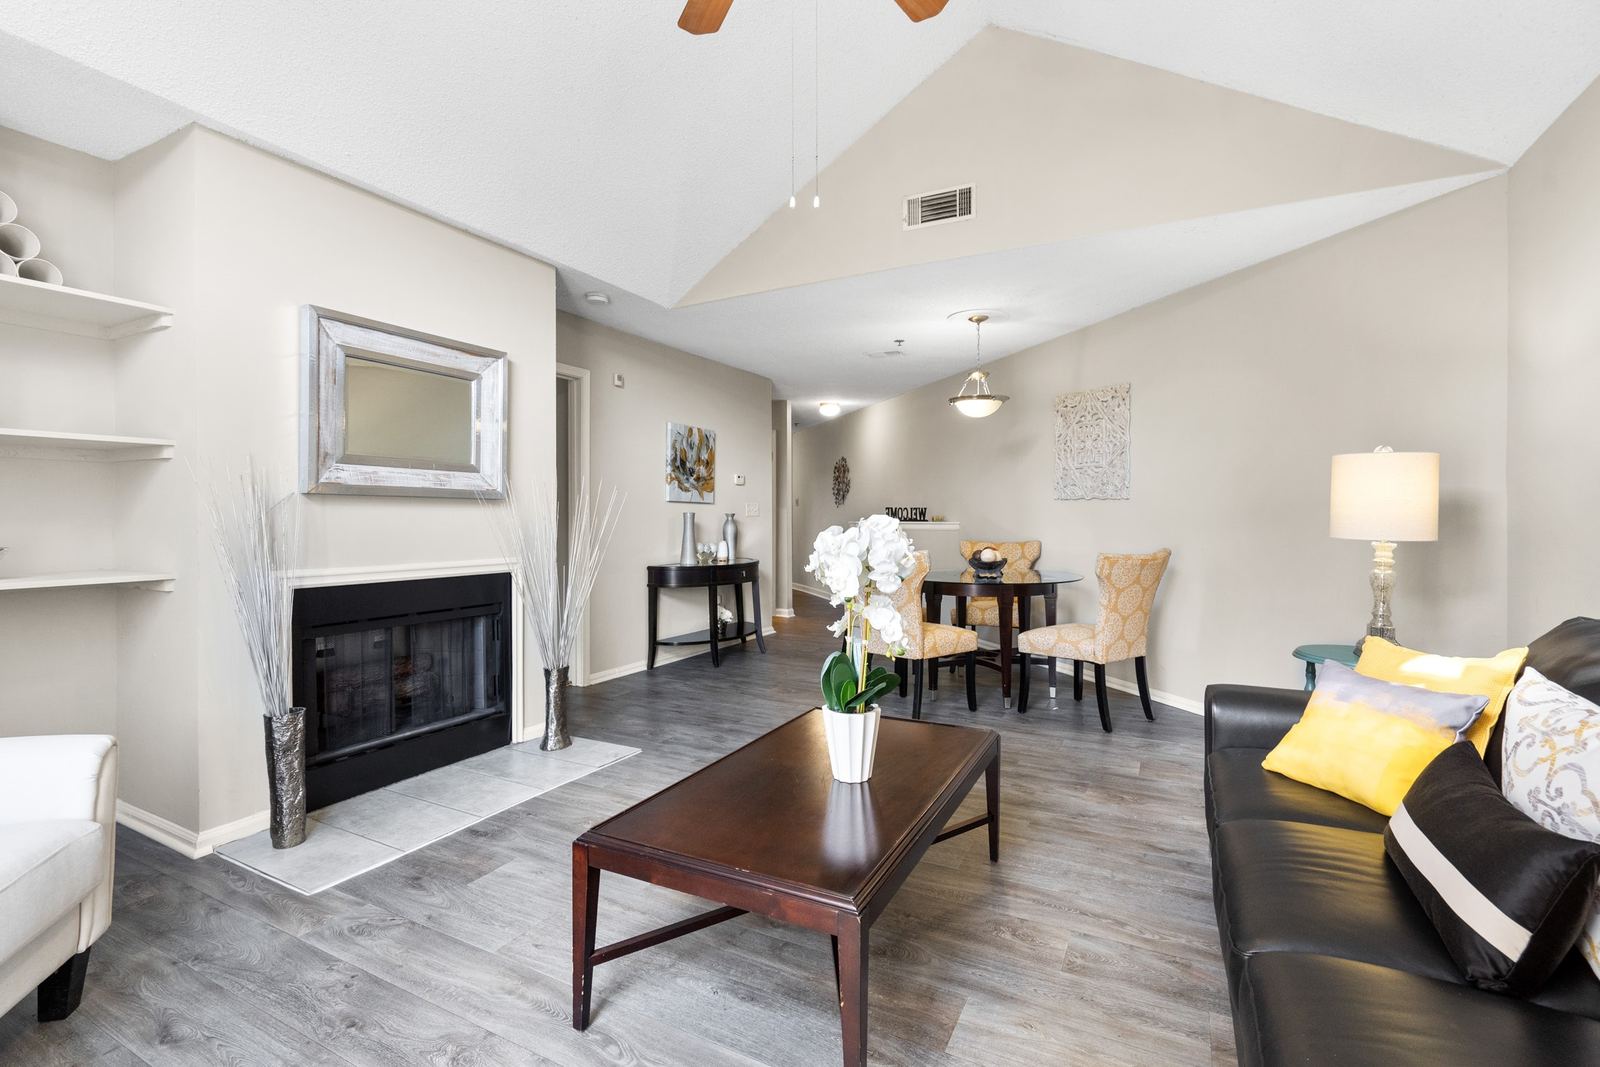
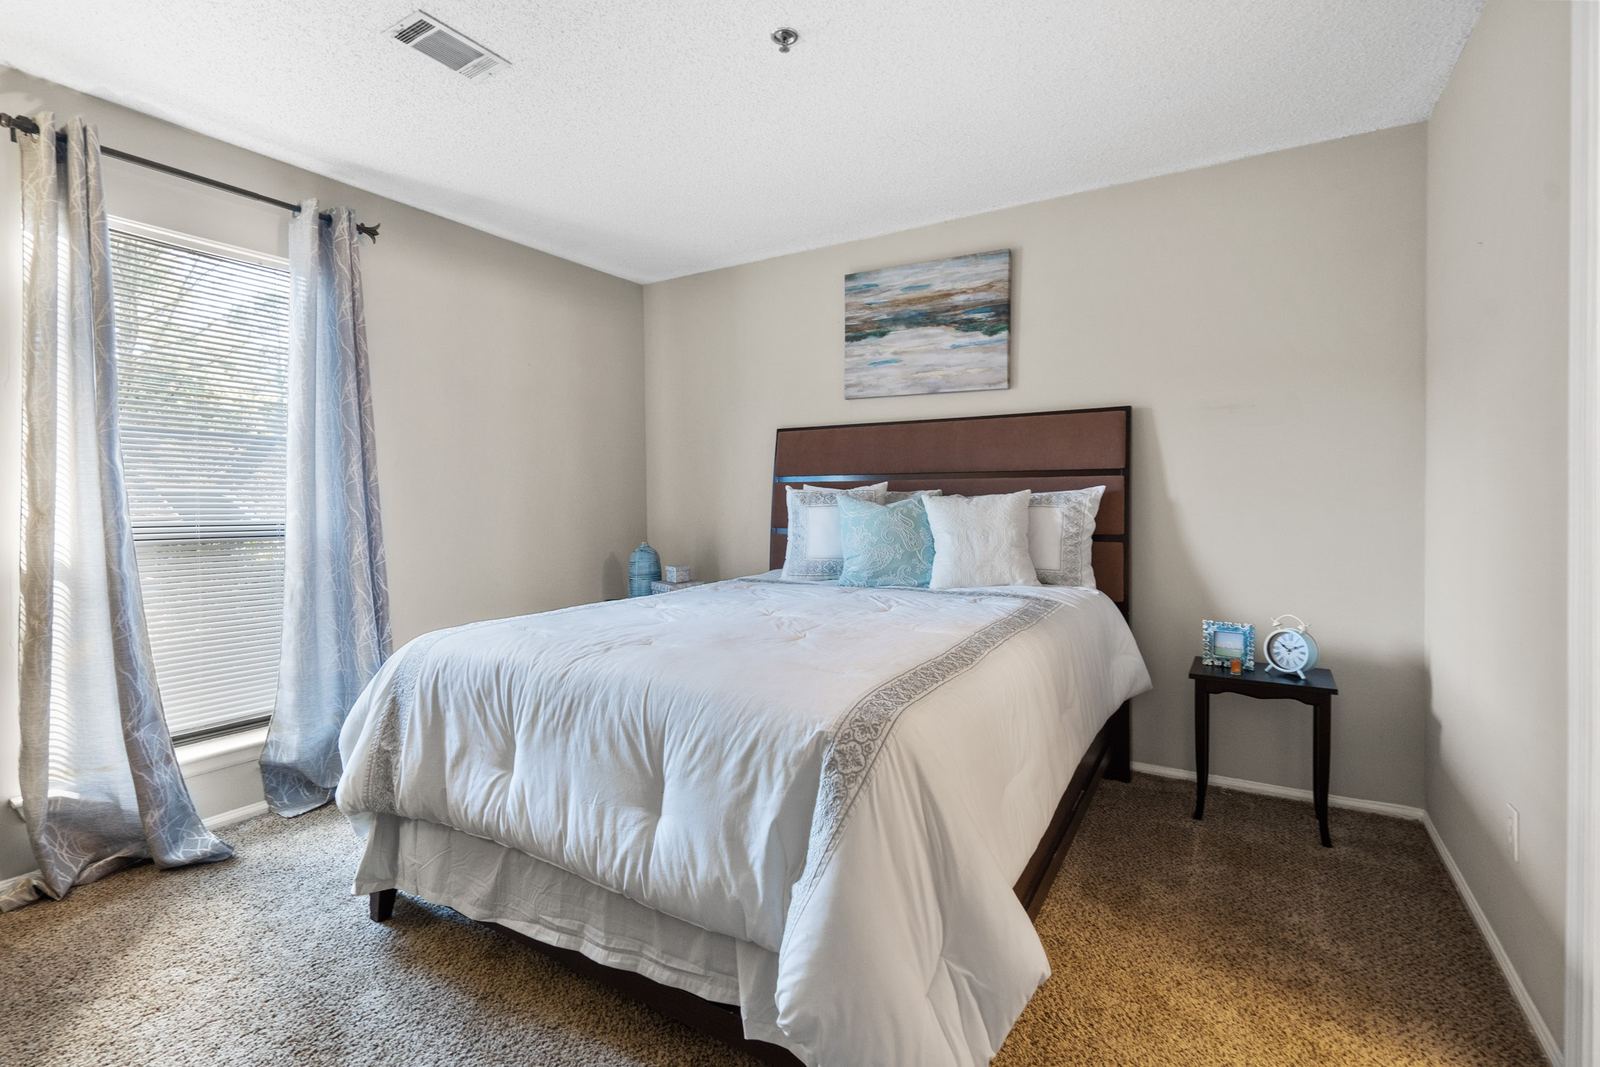
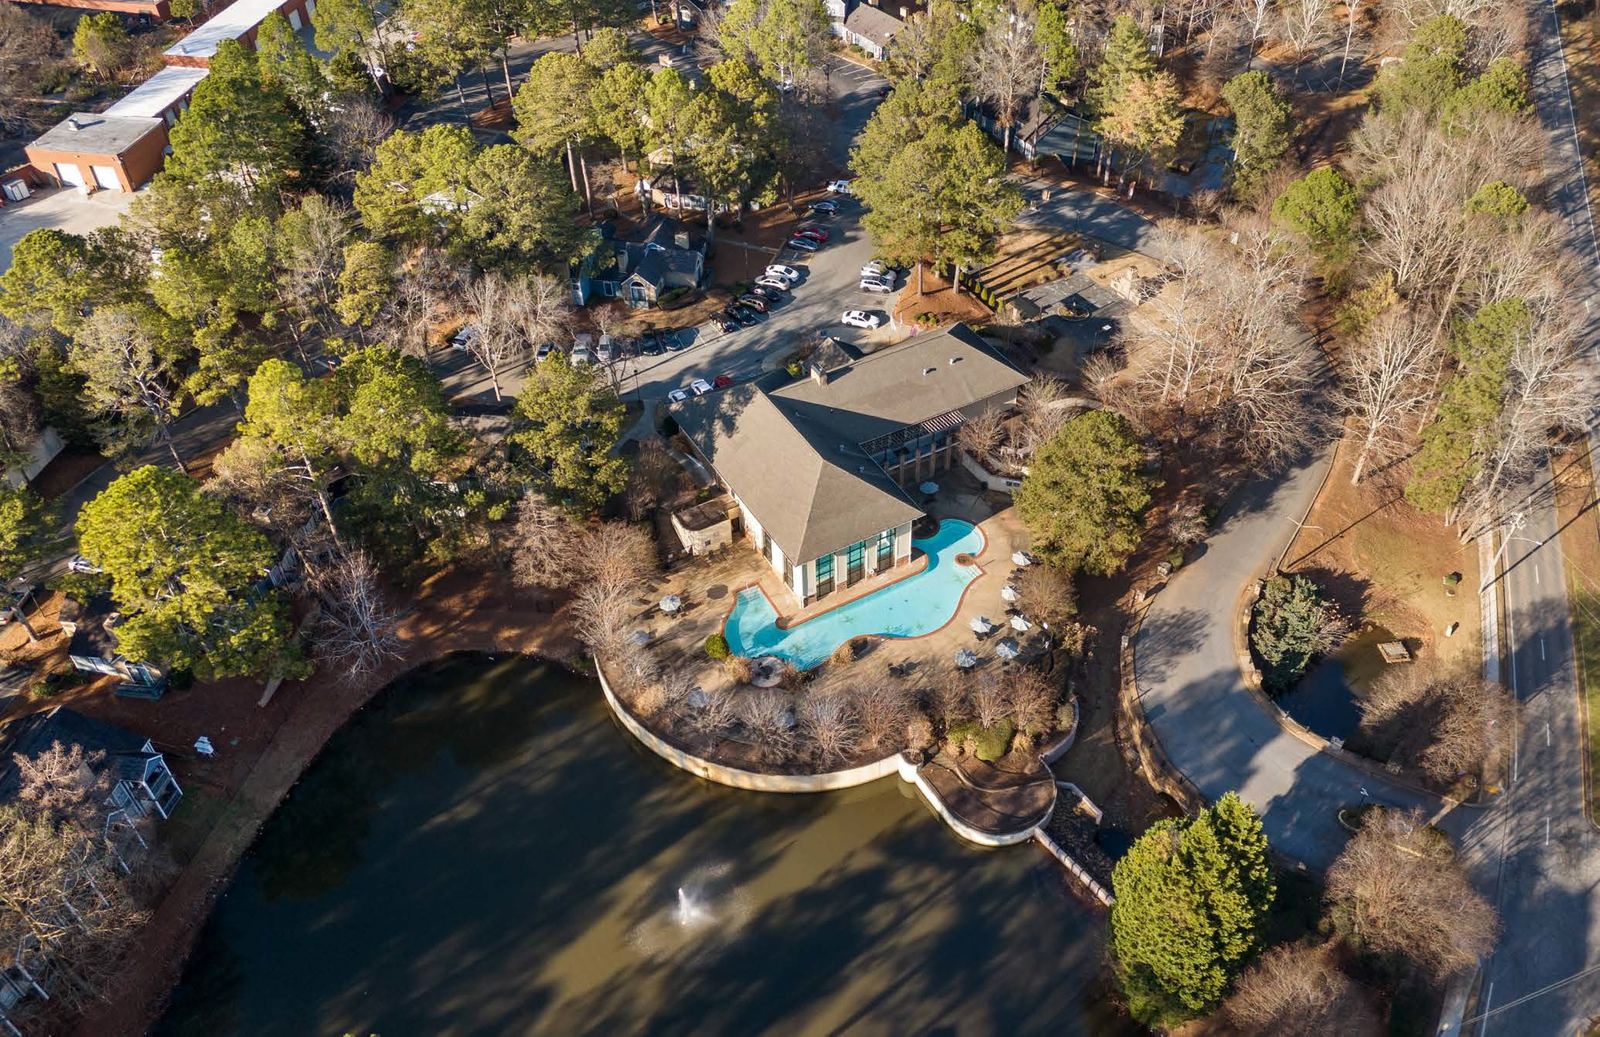
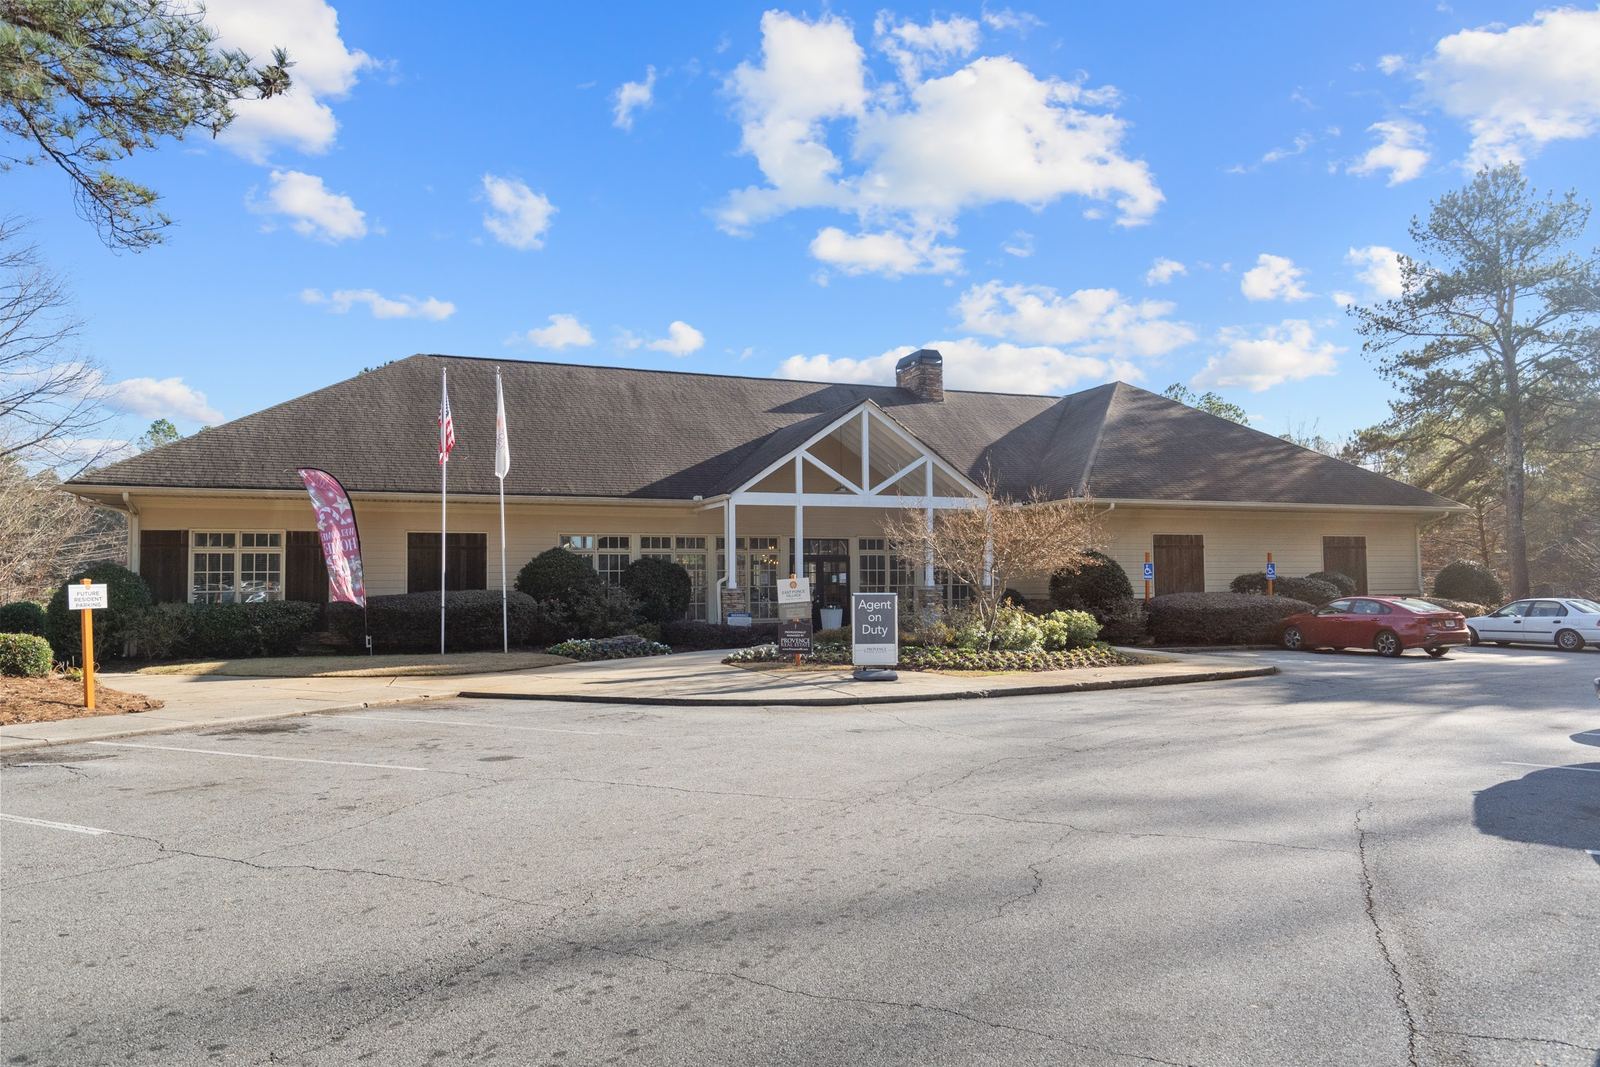
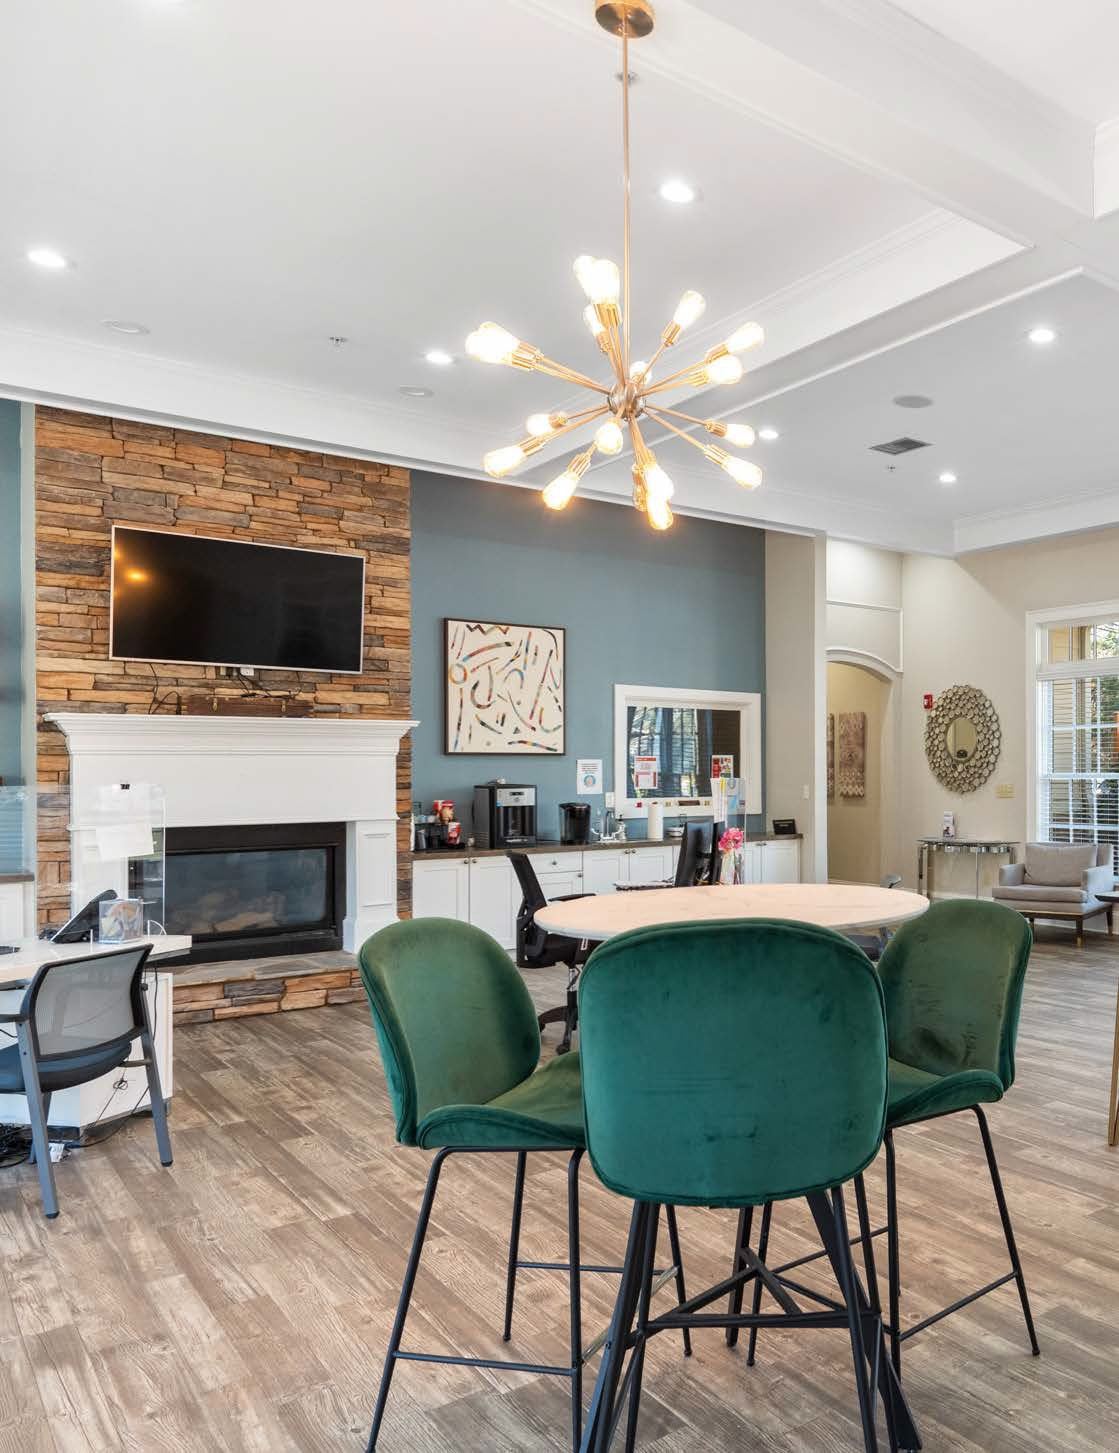
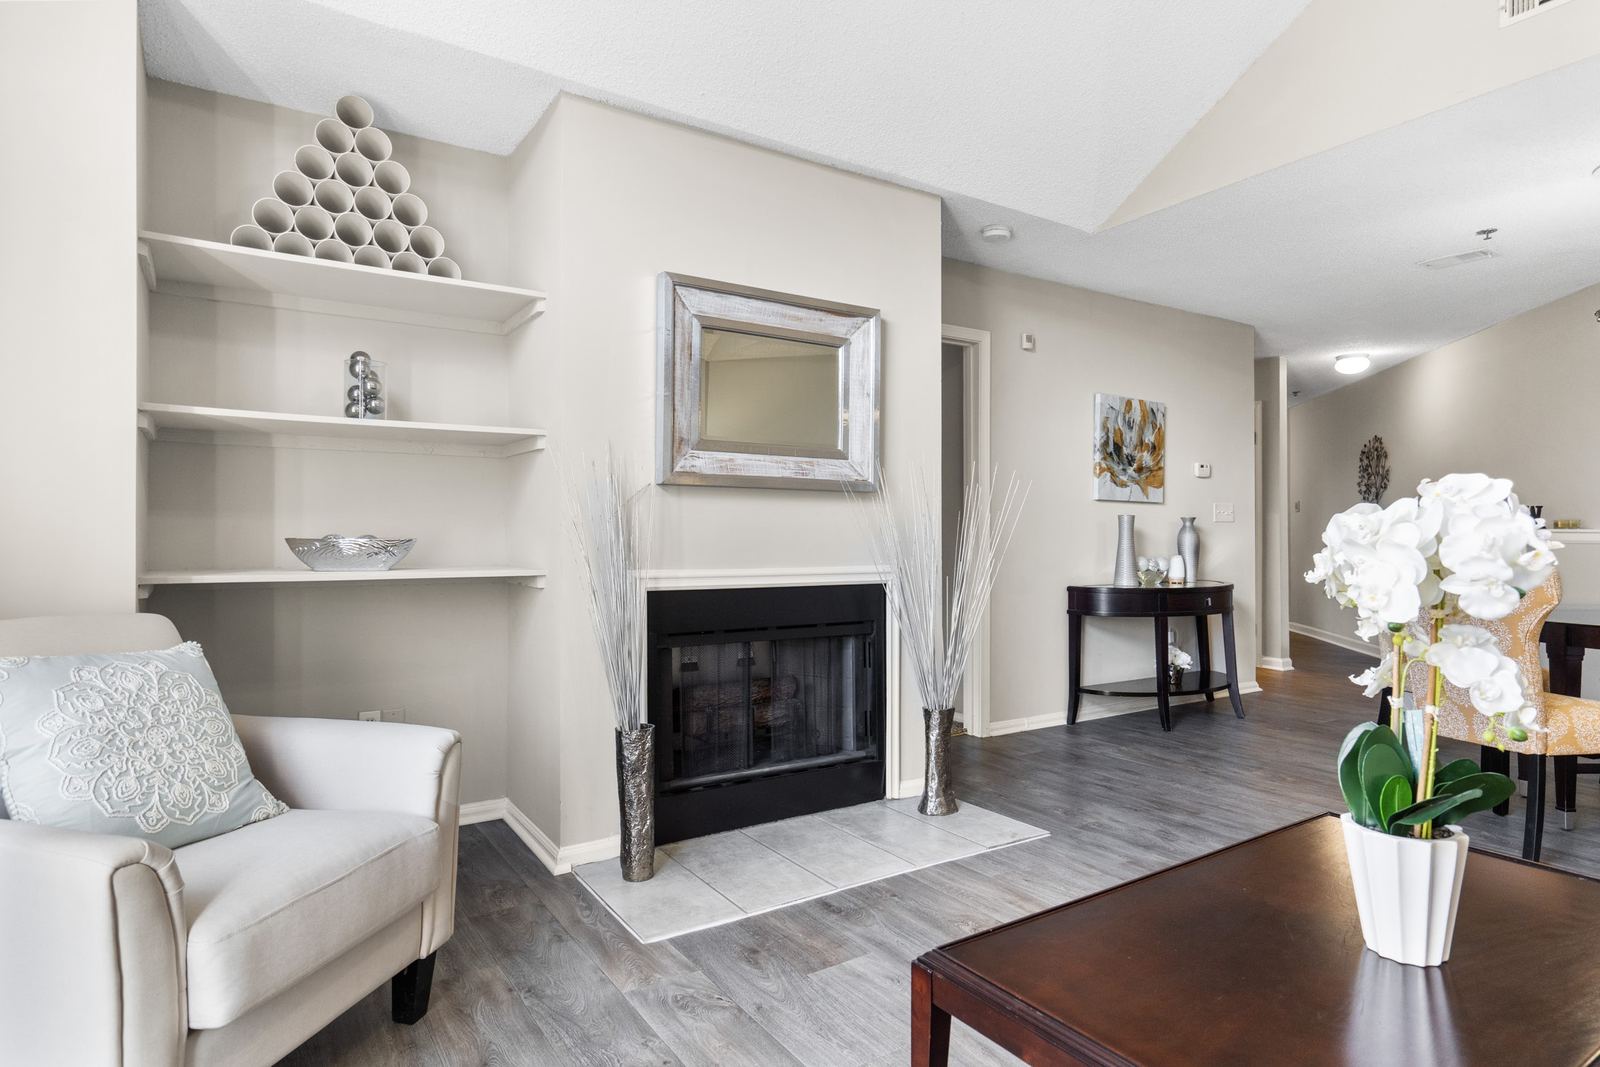
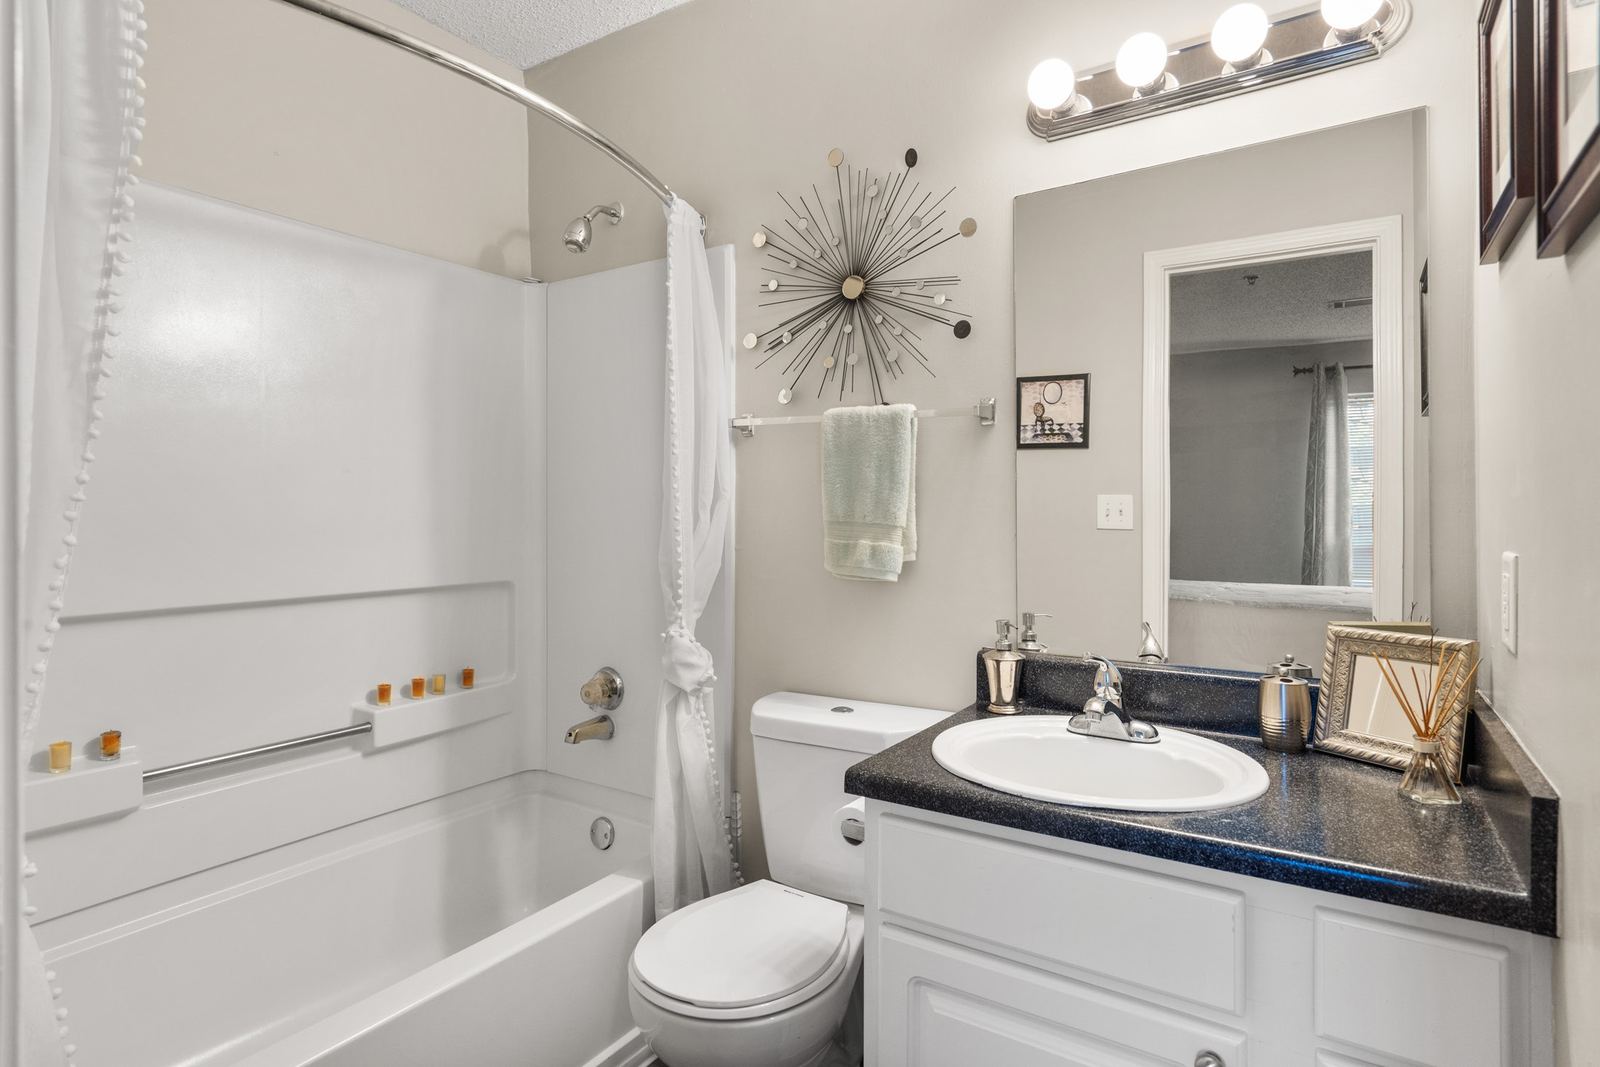
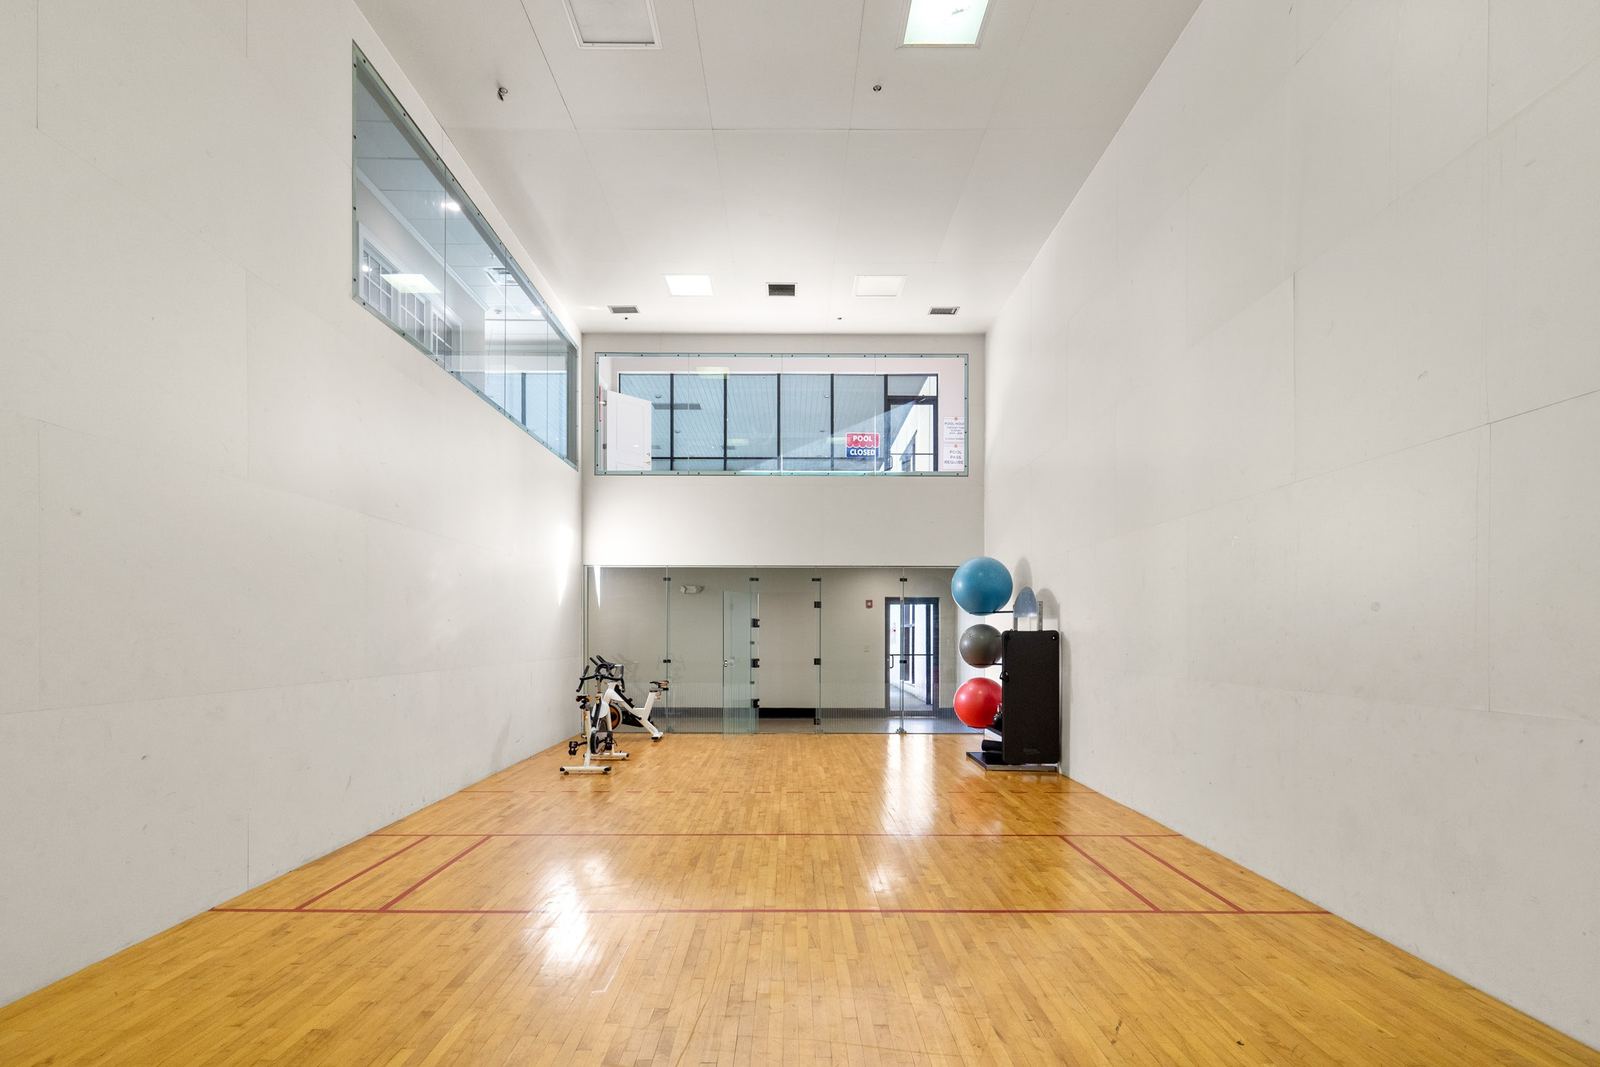
Photos from the sponsor’s offering materials.
Why invest through Jetstream’s fund
Your terms
All investors invest through Jetstream’s fund, raising capital alongside the sponsor. The targeted preferred return steps up with investment size (projected, not guaranteed).
8%
targeted pref
$50K – $499K
9%
targeted pref
$500K – $999K
10%
targeted pref
$1M+
Target returns: up to 25% IRR and up to a 3.0x multiple (projected, not guaranteed).
The numbers
Deal at a glance
- Units
- Nearly 1,000 (997); built 1987–1989
- Purchase price
- $73.0M, closed (~$73K per unit)
- 2023 appraisal
- $122.1M as-is (Apr. 2023, MAI, for a Fannie Mae loan)
- Basis vs. appraisal
- ~40% below ($49.1M gap)
- Replacement cost
- $170K–$205K+ per unit (sponsor estimate); basis 56–64% below
- Raise
- $20M ($13M already raised) to complete the capex plan
- Target returns
- Up to 25% IRR; up to 3.0x multiple (projected)
- Timeline
- Stabilization target Apr. 2027; refinance ~Year 3. Hold 3–5 years if sold; indefinite if capital is returned at the refinance.
The first question a skeptic should ask
Why the discount exists
This was a capital problem, not a demand problem.
The prior owner spent $15.8M since 2021 on interiors and common areas, then ran out of capital: unit turns and vendor payments stopped and vacancy spiked. It was 91.5% occupied at the 2023 appraisal. We are buying at ~60% of that value, below replacement cost, to restore occupancy the asset has already achieved.
Business plan and capex scope
How the value gets restored
- Return offline units to service. About 260 down units = $3.7M+ of lost annual rent; 115+ already turned, 160+ targeted by Oct. 31.
- Lift occupancy to market. Occupancy trails the competitive set; stabilizing at 92% is projected to add $3.2M+ of annual revenue.
- Close the rent gap. In-place rent of $1,082 trails market rent of $1,243 (+$161/mo, ~15%) and is only 16.1% of 3-mile household income.
- Continue a proven renovation. Upgrading 921 units to the premium standard ($100–$150+ premiums) ≈ $1.1M/yr at the low end.
- Operations and amenities. Amenity and water-main upgrades; bulk internet, valet trash and pet-rent income; tighter collections.
Sponsor pro forma (projected)
Where the NOI comes from
Net operating income on the $73M purchase price: 4.7% in Year 1, 8.4% in Year 2, 9.9% in Year 3 and 10.5% in Year 5. Of the $4.33M Year 1–3 revenue gain, ~79% is recovery (vacancy, loss-to-lease, bad debt, concessions) and only ~16% is market-rent growth, held to 1.6–3.0% a year (vs. Atlanta’s 4.1% 5-year average). The case rests on filling and collecting, not the market.
Projected, not guaranteed
How investors are paid
- 1Years 0–3: pref accrues
No distributions for about 3 years while the preferred return accrues. Cost segregation is done, with a possible year-one depreciation benefit (consult your CPA).
- 2~Year 3: refinance
A planned agency refinance is projected to pay investors their accrued pref and return their capital (stated goal: at least 80% and up to 100%).
- 3After the refi: stay in
Investors keep their interest and receive ongoing cash-flow distributions until the property is sold.
Read this part twice
Key risks and mitigants
Depends on Year-3 NOI and credit markets.
~40% below the 2023 appraisal and replacement cost; no forced sale (indefinite hold allowed).
Year-1 vacancy is 23% of gross potential rent.
115+ offline units turned; new management; the 92% target is near the 91.5% achieved in 2023.
Rent growth below the market average; rent is 16.1% of local income; bad debt modeled at 3.3% of gross potential rent in Year 1, 1.0% by Year 3.
1987–89 vintage.
$15.8M already invested by the prior owner; the $20M raise ($13M already raised) is sized to complete the plan.
No distributions for ~3 years.
The 0.5% asset-management fee ($365K/yr) and the property-management fee are in pro forma expenses.
Ready to look closer?
Get the full Deal Highlights and book a call with Brett. No obligation.
Get the deal highlightsAccredited investors only (Rule 506(c)); accredited status will be verified. This is not an offer to sell securities; any offering is made only through official offering documents. Projections are not guaranteed. Figures are summarized from the sponsor’s offering materials and a 2023 third-party appraisal, have not been independently verified, and may change. Investors may lose some or all of their investment.